Why Your Profitable Business Is Still Running Out of Cash
Can a business be profitable and broke at the same time?
It happens all the time, and it has little to do with how well the business is run. The distinction is simple but often overlooked: profit and cash aren’t the same thing.
If your P&L looks solid, but payroll week tightens your belt and key equipment purchases keep getting pushed back, this is likely why.
Key Takeaways
Profit isn't the same as cash. Your business can be profitable and still struggle to pay bills.
Cash usually gets delayed, not lost. Unpaid invoices, inventory, growth, and loan payments all tie up cash.
A cash flow statement and 13-week forecast help you see problems coming and act before cash gets tight.
Why Profit and Cash Don’t Always Match
Picture a typical month for a service or product-based business. Most people imagine making a sale and receiving payment immediately. But for most business owners and operators, that isn’t reality.
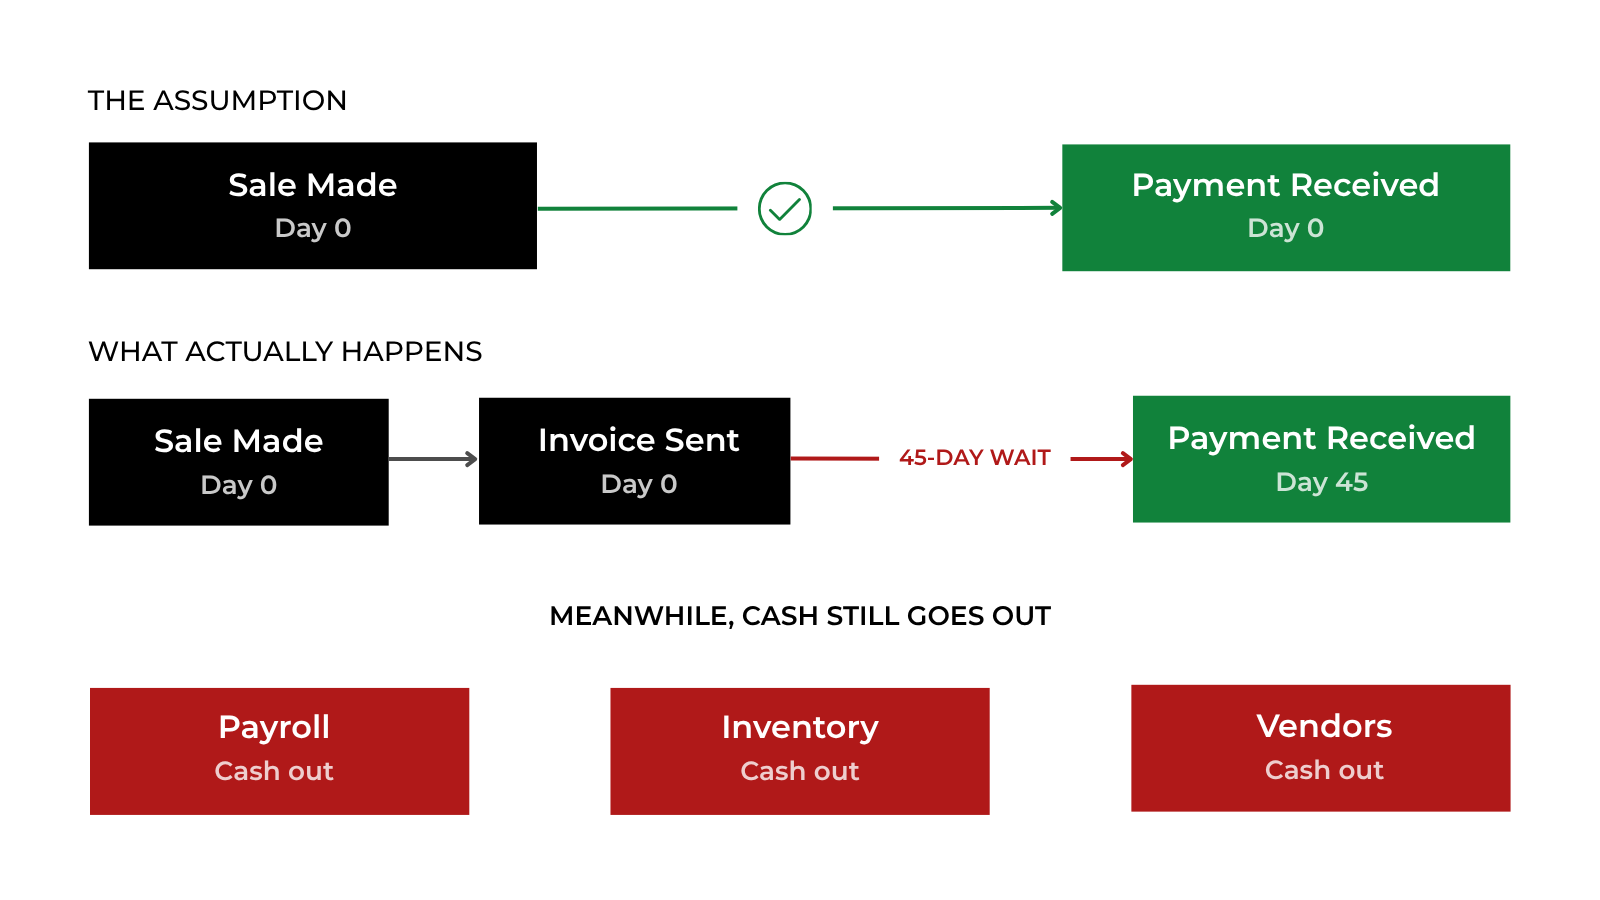
On paper, there’s plenty of profit, but your actual bank account is stretched thin.
A few patterns create or worsen the mismatch:
Unpaid invoices. The work is done and billed, but you’re waiting on payment.
Cash sitting in inventory. You already paid for it, but there’s no cash until it sells.
Growth outpacing collections. The faster you add new sales, the more of them sit uncollected at any given moment, all while expenses scale with growth.
Debt payments that aren’t on your P&L. Loan principal is a cash outflow, but it never shows up as an expense on your income statement.
These are all normal parts of running a business. They can become problematic when no one’s tracking the timing of cash coming in and going out.

Where the Cash Goes
Most accounting systems make it easy to monitor your P&L. Understanding cash flow usually takes an additional report and regular review.
Glancing at revenue and net income takes seconds, but understanding where your cash went requires a cash flow statement, a rolling forecast, and someone to review both regularly.
Without that visibility, the first sign of trouble is when you feel it: a tight payroll week, a maxed-out line of credit, or a shelved growth decision because the timing feels wrong.
Say a business brings in $80,000 in sales for the month, with $60,000 in costs. That's a solid $20,000 in profit on paper.
But when $50,000 of that revenue sits in invoices that take 45 days to be collected, you still have bills to pay.
Your $60,000 in costs is up against $30,000 in cash. Payroll, inventory, and vendor payments still have to go out this month, in cash, right now.
On paper, the business earned $20,000, but in the bank, it’s $30,000 short.
How to Get Ahead of It
Review a cash flow statement every month, alongside your P&L. Your P&L tells you if the whole business is working, but cash flow will tell you whether you’ll make it in the next 30, 60, and 90 days.
Watch your accounts receivable. If invoices consistently take longer to collect than payment terms allow, that delay puts pressure on cash flow despite strong revenue.
Build a rolling 13-week cash forecast. This helps you spot potential cash shortages before they become immediate problems.
Track debt service separately from operating expenses. Loan payments reduce cash but not reported profit, making them largely invisible.
Practical Ways to Address the Wait
You can also improve cash flow by reducing the time between completing the work and collecting payment.
1. Ask for deposits or progress payments up front. On larger jobs, collecting even 30–50% before the work starts reduces the amount of time your cash is tied up in an invoice.
2. Push for shorter payment terms with your customers. Net 45 or Net 60 terms often feel like the industry standard, but they're negotiable. Moving even a portion of your customer base to Net 30 pulls money into the bank sooner.
3. Negotiate longer terms with your own vendors. If your customers take 45 days to pay, paying your suppliers on a similar timeline keeps more cash in your account over the same period, rather than paying out fast on one side while waiting on the other.
4. Use a line of credit as a bridge. Drawing on a line of credit to cover a known busy stretch and then paying it down as invoices are collected is a normal, healthy use of the tool.
Want More Practical Business Insights?
Every month, Protect Your Profit shares straightforward guidance on tax planning, cash flow, and financial decisions to help business owners make better decisions.
Frequently Asked Questions (FAQs)
Q: Can cash-basis accounting solve cash flow problems?
A: Not necessarily. Most established businesses use accrual accounting for a good reason: it matches revenue to the period in which it was earned, which matters for taxes, loans, and understanding true profitability. The solution is to review cash flow alongside your accrual P&L.
Q: Can a profitable business run out of cash even if it isn’t growing?
A: Growth often makes the problem more noticeable, but any business with a lag between billing and collection can run into it. Long payment terms, slow-paying customers, or seasonal swings in inventory can create the same mismatch at any size.
Q: Can my CPA help me improve cash flow?
A: Yes. Many CPAs offer cash flow planning in addition to tax and accounting services. A cash flow forecast, accounts receivable review, and regular financial analysis can help you identify potential shortfalls before they affect day-to-day operations.
Content in this material is for general information only and is not intended to provide specific advice or recommendations for any individual.
Want tax & accounting tips and insights?
Sign up for our newsletter.